


Mattress Financing Options: A Practical Guide for Shoppers

A new mattress rarely arrives at a convenient time. A family may need better support now, while grocery costs, utility bills, school expenses, and an unexpected repair are already competing for the same paycheck. The right mattress financing option can make the purchase manageable, but the wrong plan can turn a reasonable monthly payment into a painful balance later.
At BILTRITE, the useful question is not only, “What payment gets this mattress home?” It's, “What payment can the household keep making if life gets expensive?” That distinction separates a helpful financing plan from a financial headache.
Table of Contents
- Why More Milwaukee Shoppers Are Financing Their Mattress
- The Four Main Mattress Financing Paths Explained
- Comparing True Cost Across Each Financing Type
- The Deferred-Interest Trap Most Shoppers Miss
- Choosing the Right Plan for Your Budget
- How to Apply and What to Expect in the Showroom
- Smart Tips Before You Sign and a Visit to BILTRITE
Why More Milwaukee Shoppers Are Financing Their Mattress
On a Saturday afternoon in the Greenfield showroom, a family from Wauwatosa tests a queen mattress set priced at $2,400. Everyone agrees that the bed offers the support and comfort the household needs, but the full price feels difficult beside fixed grocery and utility bills. A monthly payment looks more approachable, yet the family still needs to understand what that payment will cost over time.
That family has several broad paths available:
- Store credit: A retail account may offer a promotional period or fixed installment plan.
- General-purpose credit: An existing card or personal borrowing option can spread out the purchase.
- Buy now, pay later: A short installment plan may divide the transaction into scheduled payments.
- Lease-to-own: A household can use a rental-style agreement with a path toward ownership, though the total cost may be substantially higher.
Retail financing has become a familiar part of durable-goods shopping. The U.S. retail credit balance was estimated at about $130 billion at the end of 2023, representing more than 2.5% of total outstanding consumer credit. The Federal Reserve also estimated that nearly 85 million people held a retail credit account, with roughly 150 million accounts open. The median balance was $194, and the median monthly payment was $29. These figures come from consumer retail financing data and analysis.
Those figures don't mean every mattress purchase should be financed. They show that retail credit is a mainstream payment habit, especially for household goods that shoppers expect to use for years. A mattress can be worth financing when the purchase solves an immediate need and the payment fits comfortably after ordinary bills and savings goals.
The practical rule: Financing should preserve cash flow, not disguise a purchase that the household can't sustain.
BILTRITE has served the Metro Milwaukee community as a fourth-generation, family-owned business since 1928. Its local approach matters here because shoppers can discuss the mattress, the payment, and the fine print with a sales associate in person. The showroom experience also gives families a chance to understand why buying locally matters when choosing a new mattress, rather than treating financing as a checkout shortcut.
The Four Main Mattress Financing Paths Explained
Each financing category solves a different problem. The lowest advertised payment isn't automatically the least expensive choice, and approval speed doesn't tell shoppers what the agreement will cost.
Store credit
Retail store credit commonly combines a credit application with a promotional offer. Some plans use true installment financing, while others defer interest during a promotional window. Promotional periods can run from 6 months to 2 years, and some store-branded programs carry a post-promotion purchase APR around 34.99%. The consumer guidance on deferred-interest store credit explains why the agreement's interest language matters more than the large “0%” displayed in advertising.
Approval may be fast, but applicants should expect identity details, income information, address information, and a credit review. The agreement should state whether the inquiry is soft or hard, when payments begin, and what happens to any remaining balance.
General-purpose credit
An existing credit card can be convenient because no new retail account may be necessary. The risk is that a promotional purchase can sit beside other spending, making the payoff deadline harder to track. A general card's introductory APR also ends, and the remaining balance can move to the standard APR afterward, as explained in guidance on introductory 0% credit offers.
A personal installment loan can offer a fixed payment and a defined payoff date, but approval, pricing, fees, and term depend on the lender and the applicant's profile. It should be compared by total repayment, not by payment size alone.
Buy now, pay later
BNPL plans generally divide a purchase into scheduled installments. Available offers can range from 0% to 36% APR, depending on eligibility and the transaction. Some plans require a down payment, and payment timing may be shorter than a traditional monthly account. The overview of mattress financing structures and BNPL terms highlights why shoppers need to confirm whether the plan is interest-free, low-interest, or subject to another cost structure.
The application may use a soft eligibility check, but the final agreement controls. The shopper should verify late-payment consequences, automatic withdrawals, and the exact number and timing of installments.
Lease-to-own
Lease-to-own contracts are not the same as conventional credit. The provider rents the mattress under a contract that may include an early-purchase option or a longer path to ownership. This approach can be available when traditional credit approval is difficult, but the total ownership cost can be much higher.
The agreement deserves line-by-line review. The applicant should ask what happens after a missed payment, whether returning the mattress ends the obligation, and how much ownership costs under each available purchase path. BILTRITE's furniture financing information can serve as a starting point for discussing available in-store pathways, but the signed agreement remains the controlling document.
Comparing True Cost Across Each Financing Type
A payment comparison only helps when it includes the full repayment picture. Every shopper should record the APR, promotional end date, required payment, fees, and final amount owed before signing.
The requested $1,800 illustration cannot be presented as a factual market comparison without a specific lender agreement. Financing terms vary by approval, purchase amount, promotion, and contract language. The following table shows what must be compared rather than inventing a payment or total cost that may not match an actual offer.
True Cost of $1,800 Mattress by Financing Type
| Financing Type | Representative APR | Term Length | Monthly Payment | Total Cost | Credit Check |
|---|---|---|---|---|---|
| True 0% APR installment plan | 0% if the agreement states true 0% APR | Stated in offer | Purchase amount divided by scheduled payments | Principal, plus disclosed fees if any | Depends on provider |
| Deferred-interest store credit | Promotional rate may be 0%, with a standard APR after promotion | Fixed promotional window | Required minimum may not clear the balance | Principal if paid in full by deadline, potentially much more if the deadline is missed | Credit application commonly required |
| BNPL installment plan | May be 0% or priced according to eligibility | Short, fixed installment schedule | Stated at approval | Scheduled installments, plus disclosed fees | Eligibility process varies |
| Lease-to-own agreement | Not comparable to a conventional APR without the contract | Early-purchase or longer ownership path | Contract-specific | Can exceed the cash price materially | Provider-specific evaluation |
A true 0% plan means the agreement doesn't charge interest during the stated term, subject to its conditions. Deferred interest is different. If the shopper misses the payoff deadline, interest may be calculated from the original purchase date rather than only from the remaining balance.
The most important cost lever is simple: clear the balance before a promotional deadline whenever the agreement requires it. A shopper should divide the financed principal by the number of promotional months, then add a small personal cushion if possible. If that payment doesn't fit after housing, food, utilities, transportation, and savings, the plan is too aggressive.
A longer term can lower the monthly payment while increasing the chance of carrying a balance into a higher-cost period. Retail programs also commonly tie promotional terms to purchase thresholds. One published example lists 6 months on purchases of $199 or more, 24 months at a $999 minimum, 50 months at a $2,299 minimum, and 72 months at a $3,199 minimum. The published financing threshold example demonstrates why the purchase amount and term must be read together.
For shoppers considering rent-to-own arrangements, BILTRITE's rent-to-own information belongs in a separate comparison category. A lease-style contract shouldn't be described as a low-cost substitute for credit without reviewing its total ownership amount.
The Deferred-Interest Trap Most Shoppers Miss
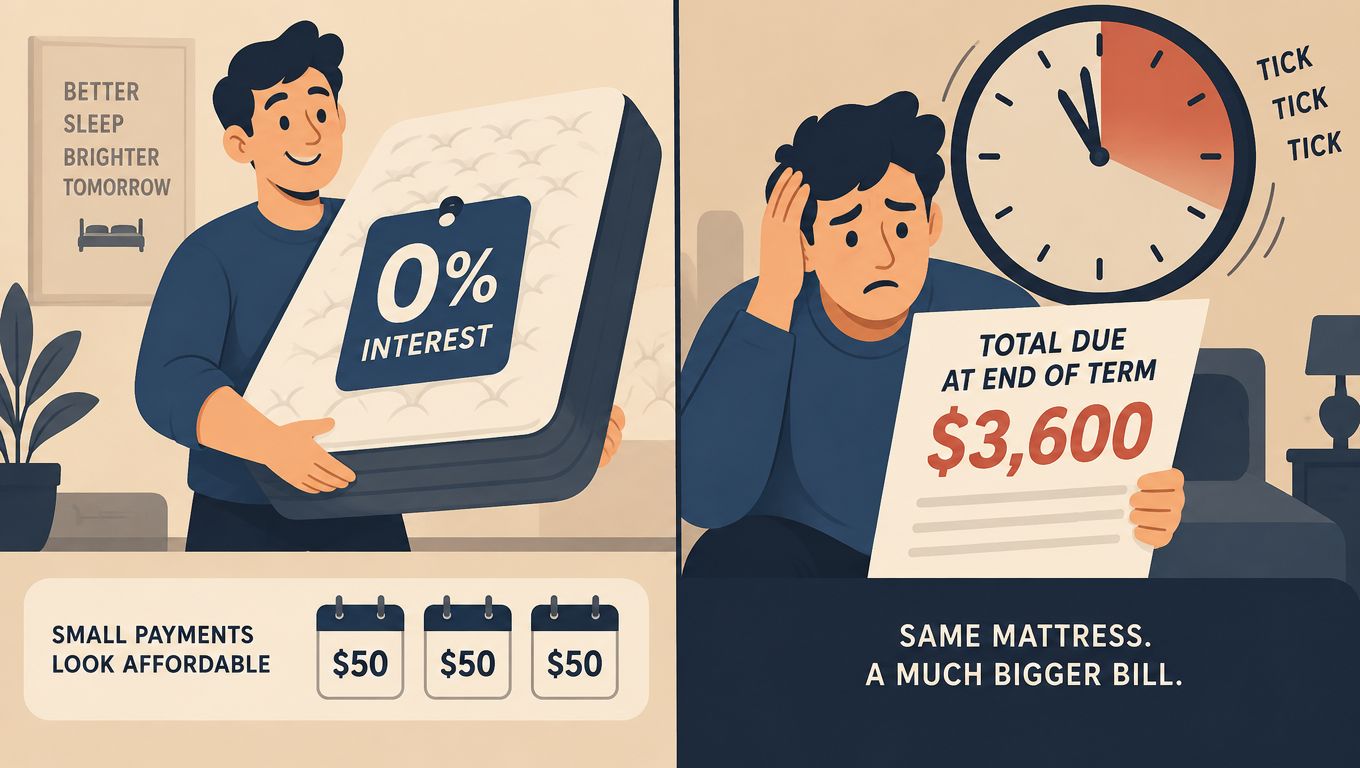
The lowest monthly payment can be the most misleading number in the room. A deferred-interest offer may display 0% during the promotion, but the customer can owe interest calculated from the purchase date if the balance isn't paid in full by the deadline.
The clock starts with the purchase, not with the customer's preferred payoff schedule. A shopper who makes only the required minimum payment may reach the end of the promotion with a balance still open. If the agreement applies deferred interest, the account can then add the accumulated interest under the contract's rules, while the standard APR may also apply going forward.
Where shoppers get caught
A missed payoff isn't always caused by reckless spending. Common problems include:
- Payment timing: Automatic payments may arrive after the shopper thinks the balance has been cleared.
- Returns: A return or exchange can take time to process, leaving the account open near the deadline.
- Added items: A protector, base, delivery charge, or other purchase can change the financed balance.
- Minimum payments: The required minimum may be far below the amount needed to finish on time.
- Household disruption: A repair, reduced work schedule, or medical bill can interrupt an otherwise workable plan.
A published mattress financing example uses a 6-month promotion for purchases from $299 to $1,998.99 and a 12-month promotion for purchases of $1,999 or more. The agreement states that interest is avoided only when the promotional balance is paid in full within the window. The example's promotional financing terms show why the exact end date and payoff amount belong on the shopper's calendar.
A true 0% APR offer, where interest isn't charged during the stated term, is easier to evaluate than deferred interest. A short BNPL plan can also be clear when the fixed installments fit the household's cash flow. Neither option removes the need to read late-fee and return terms. Shoppers who want to compare a BNPL route can review BILTRITE's information about furniture stores that accept installment payment services, then confirm the actual offer available at purchase.
Before signing: The shopper should write down the payoff date and the monthly amount needed to reach a zero balance before the promotional period ends.
Choosing the Right Plan for Your Budget
Payment resilience matters more than approval. A household may qualify for a plan and still find the payment uncomfortable after an ordinary financial surprise.
Start with the household's actual position
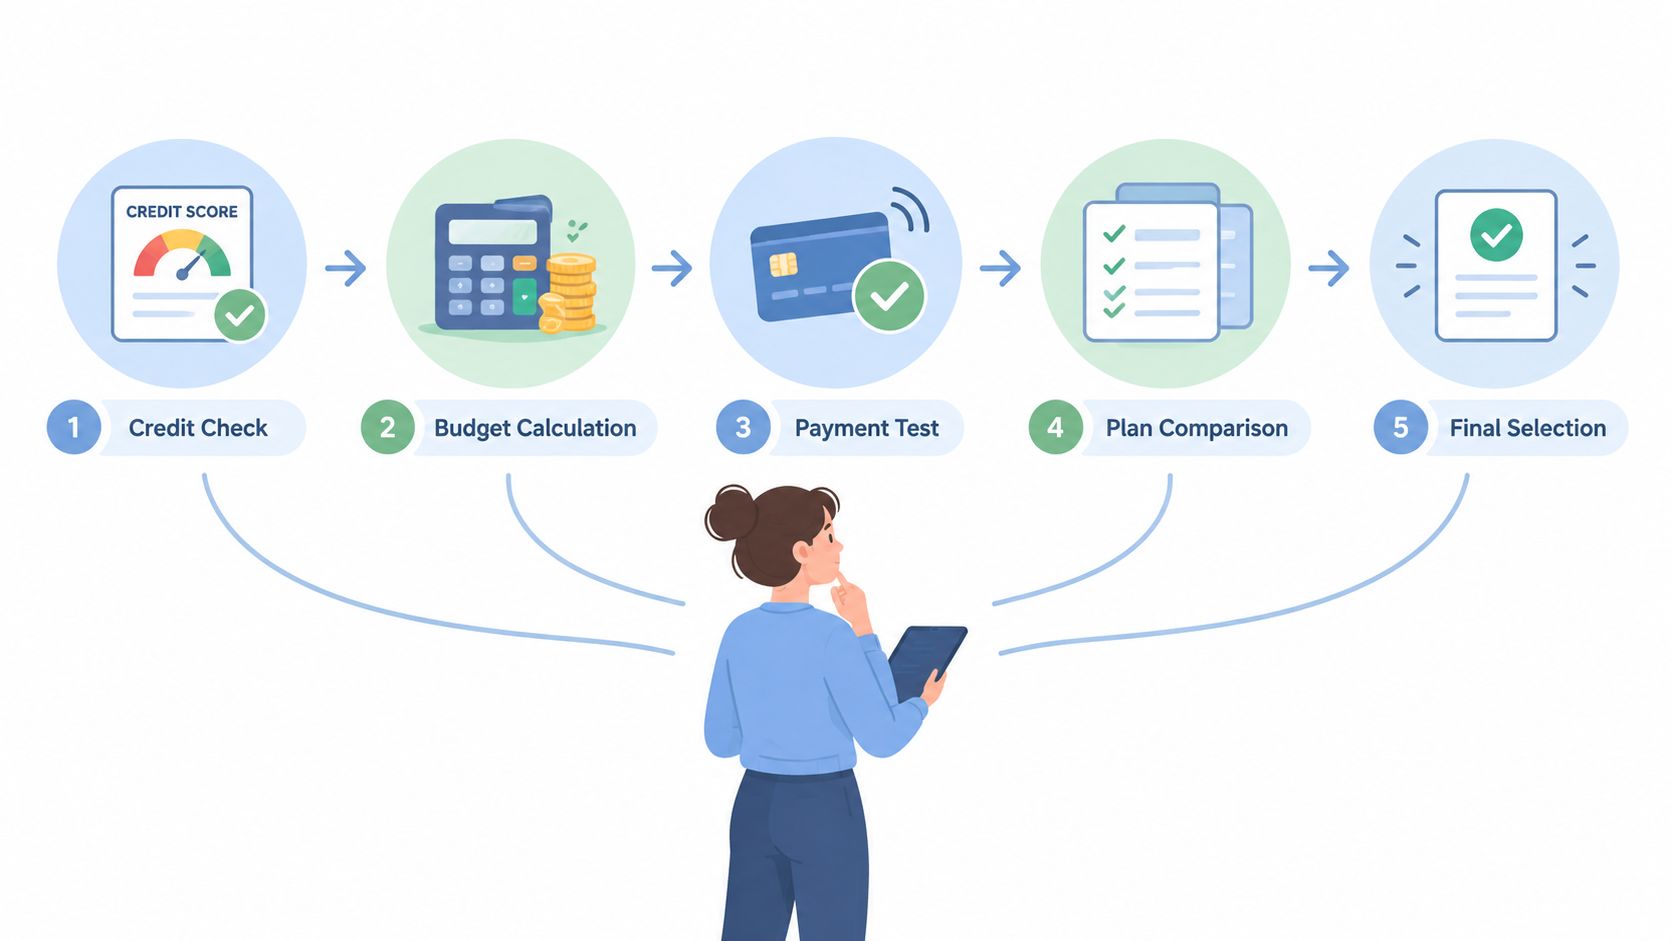
A repeatable review can happen in five steps:
Check the credit profile. A shopper should review the available credit report and score before entering the showroom. This doesn't guarantee approval, but it helps set realistic expectations about promotional offers and possible rates.
Set a sleep budget. The household should list the amount available after rent or mortgage, utilities, groceries, transportation, insurance, and regular savings. The remaining amount isn't automatically the mattress payment. A buffer must remain for ordinary surprises.
Match the term to the payoff. If the agreement has a promotional deadline, the shopper should divide the financed balance by the number of months available. The resulting amount must clear the balance before the deadline, not merely satisfy the minimum payment.
Run a disruption test. The household should ask whether it could keep paying if a paycheck arrived late, work hours fell, or a repair bill appeared. If the answer is no, the plan needs a smaller balance, a larger upfront payment, or a different term.
Inspect the complete cost. The shopper should check application fees, late fees, required down payments, optional add-ons, delivery charges, return rules, and early-payoff provisions. A lower advertised APR doesn't compensate for a payment structure the household can't maintain.
The right plan usually has a payment that feels boring rather than impressive. A modest payment with a clear end date is more useful than a very low payment that leaves the balance exposed to a high standard APR.
Use the same checklist in the showroom
A household can bring the following questions on paper or in a phone note:
- What is the exact APR? Is it true 0% APR, deferred interest, or a standard interest-bearing plan?
- What date ends the promotion? The date should be written down immediately.
- What payment clears the balance? The required minimum may not be enough.
- What happens after a late payment? The agreement should explain fees and interest consequences.
- Can the household absorb a setback? The answer should be based on real bills, not optimism.
How to Apply and What to Expect in the Showroom
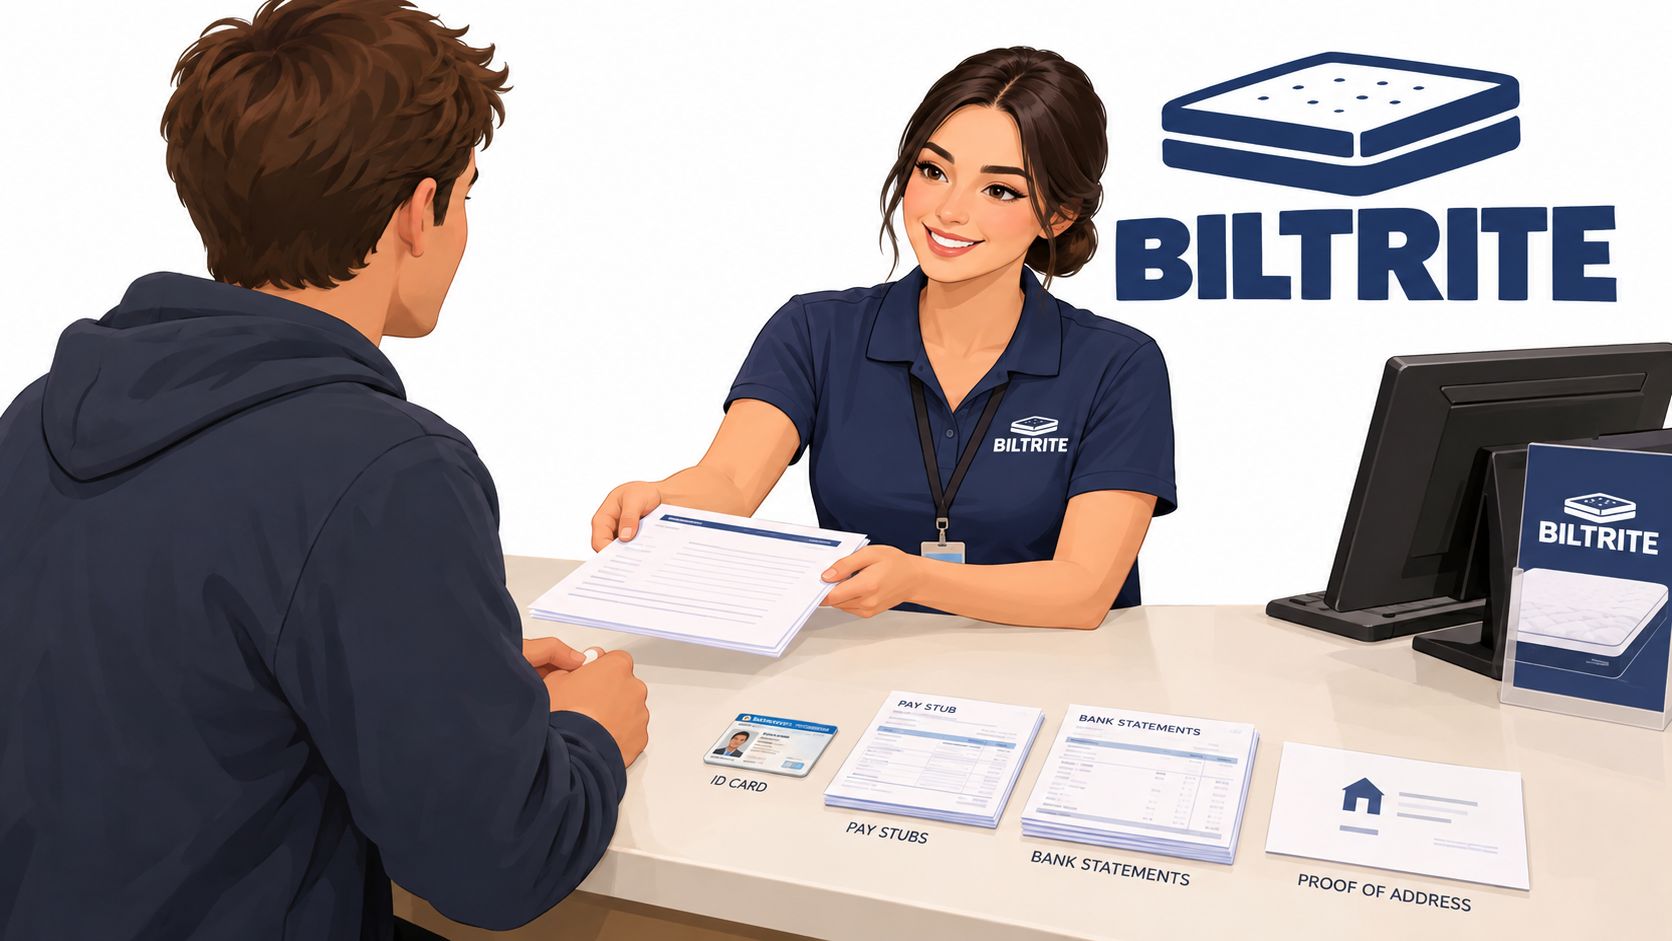
A prepared shopper can make the application process smoother. A photo ID, proof of address, and recent pay stubs or bank statements may help verify identity and income, although each provider determines its own requirements. If a pre-qualification option is available, the shopper should ask whether it uses a soft inquiry and whether the final application may use a different review.
The process generally follows a straightforward order:
- The shopper tests mattresses and chooses the sleep setup.
- The associate explains available financing categories.
- The applicant completes the relevant form or digital application.
- The provider reviews the application and returns an offer or decision.
- The shopper reads the offer line by line.
- The household confirms the payment, payoff date, APR structure, and return rules.
- The applicant signs only after the total obligation is understood.
Store credit may produce a quick decision, but speed doesn't replace review. A conventional credit application can affect the applicant's credit profile depending on the inquiry. A lease-style provider may focus more heavily on current income and payment capacity than on a traditional score. A BNPL application may present a short installment schedule, but that schedule can still strain a household if several other obligations are due at the same time.
Fine print worth reading twice
The agreement should answer five questions clearly:
- APR type: Is the offer true 0% APR or deferred interest?
- Promotion length: What is the exact final date for avoiding interest?
- Late consequences: Are there fees, penalty terms, or changes to the promotion?
- Early payoff: Can the shopper pay ahead without a charge?
- Returns and exchanges: How do returns affect the open financing balance?
Before applying, shoppers should also learn how to test a mattress in a showroom. Comfort remains the first decision. Financing only determines how the chosen mattress is paid for.
Smart Tips Before You Sign and a Visit to BILTRITE
A sound financing decision starts with the mattress, not the promotion. A household should test support, firmness, sleep position, and movement response before discussing payment. A low-cost plan attached to an uncomfortable mattress is still a poor purchase.
BILTRITE's Greenfield showroom gives shoppers access to a large mattress department with over 60 models and more than 500 mattresses in stock, along with sales associates whose combined experience exceeds 400 years. The selection includes small-scale options, heavy-duty choices, and flip-able or two-sided mattresses. Families can also ask whether a qualifying set includes value extras such as old mattress removal, white-glove delivery, or a complimentary protector or heavy-duty frame.
Keep the financing conversation grounded
The associate should be able to help shoppers compare:
- Payment size: What fits after the household's normal bills?
- Payoff timing: Can the balance reach zero before the promotion ends?
- Sleep setup: Does the purchase include only the mattress, or also a base and necessary accessories?
- Delivery needs: Will the household need in-home delivery or removal of the old mattress?
- Furniture fit: Does the bedroom need small-scale or heavy-duty furniture as part of the same project?
BILTRITE is a local, family-owned showroom at 5430 West Layton Avenue in Greenfield, Wisconsin. The store emphasizes affordable, better-quality furniture, including USA-made, Amish-made, and solid-wood pieces, alongside its mattress department. It doesn't sell online, and the showroom is closed on Sundays and Mondays so the family business can protect time with family.
The most responsible financing choice is the one that leaves room for real life. A shopper who can comfortably make the payment, understands the payoff deadline, and has checked the total cost can move forward with confidence. A shopper who needs the lowest possible payment with no room for disruption should pause and adjust the purchase before signing.
BILTRITE Furniture-Leather-Mattresses offers a broad in-store mattress selection, experienced guidance, and financing conversations built around the household's actual budget. Visit BILTRITE Furniture-Leather-Mattresses in Greenfield to test mattresses, review the payment terms in person, and find a sleep setup that fits both the bedroom and the monthly plan.